9 Daily Habits of Financially Fit Seniors That Keep Nest Eggs Safe (Latest Guide)
Discover the 9 daily financial habits that Canadas most financially secure seniors practice to protect their savings, be…
Read article →Maximize your retirement savings and tax refunds. Calculate your 2026 contribution room (18% of 2025 income, max $32,490), estimate tax savings based on your province, and see your after-tax contribution cost. Updated for 2026 limits and provincial tax brackets.
The 2026 RRSP contribution limit is $32,490, which is 18% of your 2025 earned income, whichever is lower. This is a 4.1% increase from the 2025 limit of $31,560. Any unused room carries forward indefinitely.
For the 2025 tax year (filed in 2026), the deadline is March 2, 2026. For the 2026 tax year, the deadline is March 1, 2027. Contributions made in the first 60 days of the year can be claimed on either the previous or current tax year.
You can over-contribute up to $2,000 without penalty. Beyond that, excess contributions are subject to a 1% per month penalty tax until withdrawn. File Form T1-OVP to calculate any penalty.
Yes! The Home Buyers' Plan (HBP) allows first-time homebuyers to withdraw up to $60,000 tax-free from their RRSP for a down payment. You must repay the amount over 15 years, starting the second year after withdrawal.
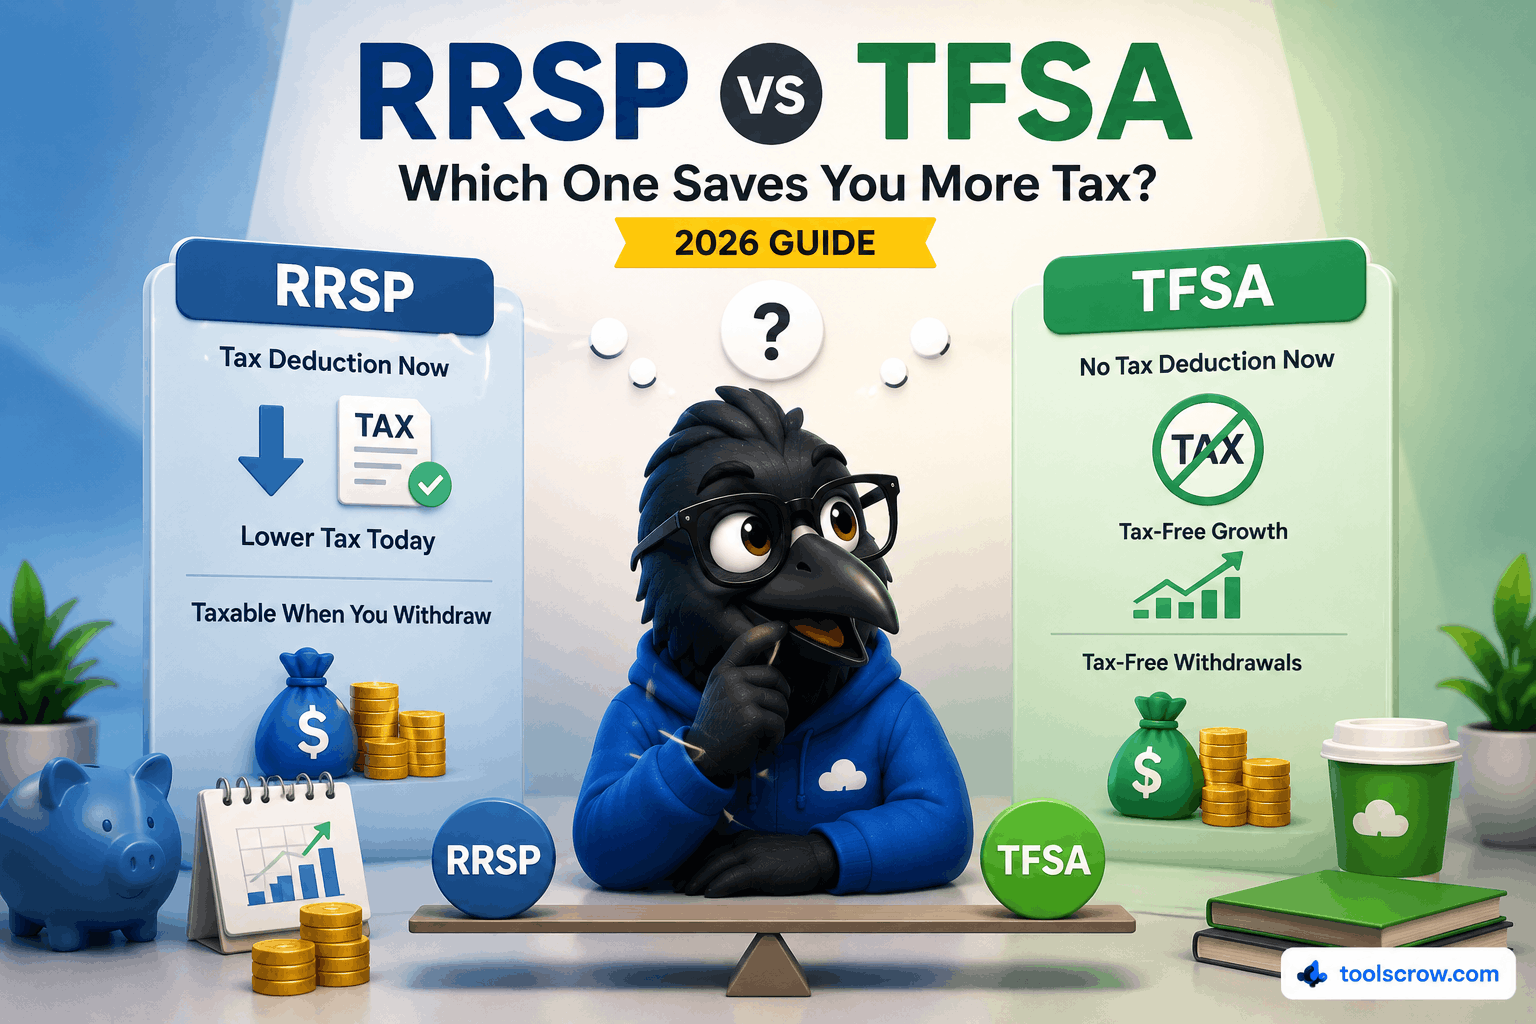
RRSP first if you're in a high tax bracket now (especially >40%). TFSA first if you're in a lower tax bracket or need flexible access to funds. Many Canadians benefit from contributing to both accounts strategically over their career.
Discover the 9 daily financial habits that Canadas most financially secure seniors practice to protect their savings, be…
Read article →Learn how to build a retirement portfolio. Covers asset allocation, dividend stocks, REITs, TIPS equivalent, CPP strateg…
Read article →RRSP vs TFSA — which account saves you more tax in 2026? Complete guide covering contribution limits, tax treatment, wit…
Read article →I was confused about how much I could contribute. This tool showed me my unused room from previous years plus what I can add this year. Really useful!